Asset Classes
Currencies you cannot settle, priced anyway
Some currencies cannot be delivered offshore. The exposure to them is real all the same, and a non-deliverable forward is how a desk takes or hedges it without needing a settlement the market will not permit.
The currency cannot be delivered offshore, so nobody tries to
A published rate on a stated date decides what the contract is worth
Only the difference moves, in a currency that can be delivered
Standard maturities, quoted out along the curve rather than spot only
See it live
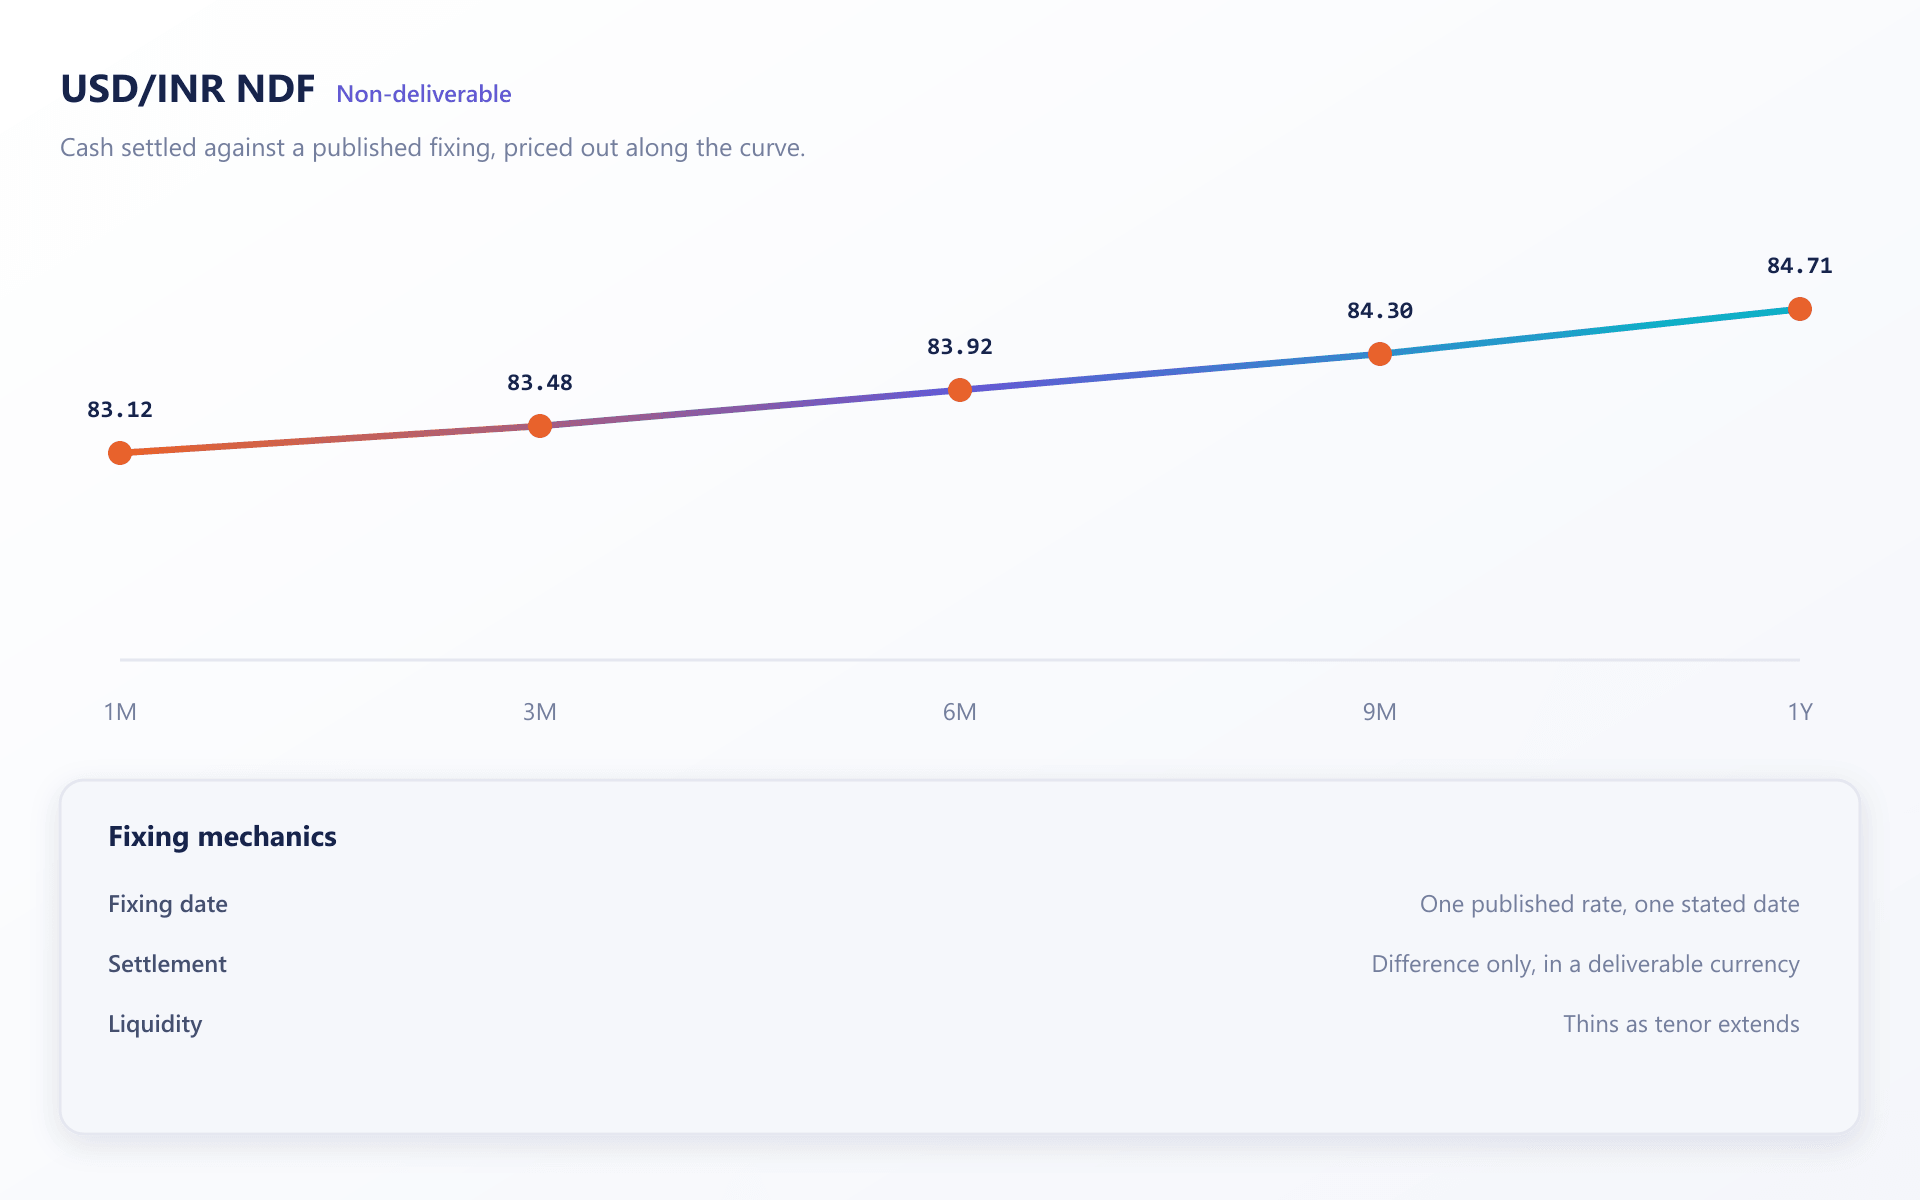
A tenor ladder, priced out along the curve
Restricted currencies quoted against a standard maturity ladder, with the near tenors and the far ones both shown rather than a single spot-like price.
How it behaves
Three things that separate this from a spot position
The fixing date is the whole event
Everything about the contract resolves on one published rate on one stated date. A desk that treats an NDF like a spot position with a longer settlement will be surprised by how much of the outcome sits in that single print.
Nothing is delivered, only the difference
There is no leg where restricted currency changes hands, which is exactly the point. Settlement happens in a deliverable currency for the difference between the contracted rate and the fixing.
Liquidity thins as you go out the curve
The near tenors behave close to spot. The far ones do not, and pretending otherwise in a quote is how a position that looked cheap to open becomes expensive to roll.
FAQ
Non-deliverable forwards: common questions
6 short answers to what teams ask before a demo.
Because the exposure is real even when delivery is not permitted. An NDF lets a desk take or hedge a view on a restricted currency without needing access to a market that would not accept the settlement anyway.
Against a published fixing on the stated date. The contracted rate and the fixing produce a difference, and that difference settles in a deliverable currency. Both sides are reading the same public print rather than negotiating a valuation.
A standard ladder rather than a single point, so a position can be placed where the exposure actually sits. The near tenors quote tightly; the far ones widen, and we would rather show that than quote through it.
The contract settles and a new one is opened at the prevailing rate. That roll has a cost, and on the far tenors it is often the largest single cost of holding the exposure, so it belongs in the decision rather than in a surprise.
In the same consolidated account as everything else, so it nets against the rest of the book rather than demanding a separate collateral pool. See the single margin account page for how that netting works.
Yes, and it is the only comparison worth making. Send the currencies and the maturities you actually deal in and the quote comes back against those rather than against the pairs that happen to price well.
Still have a question?
A specialist will answer it directly, with your set-up in mind.
Ask a specialistWhich currencies and which tenors?
Coverage in this asset class varies far more between providers than it does in spot. Send the list you actually deal in and we will confirm it before quoting.